Market Overview: Defining the Industrial Nitrogen Market Scope
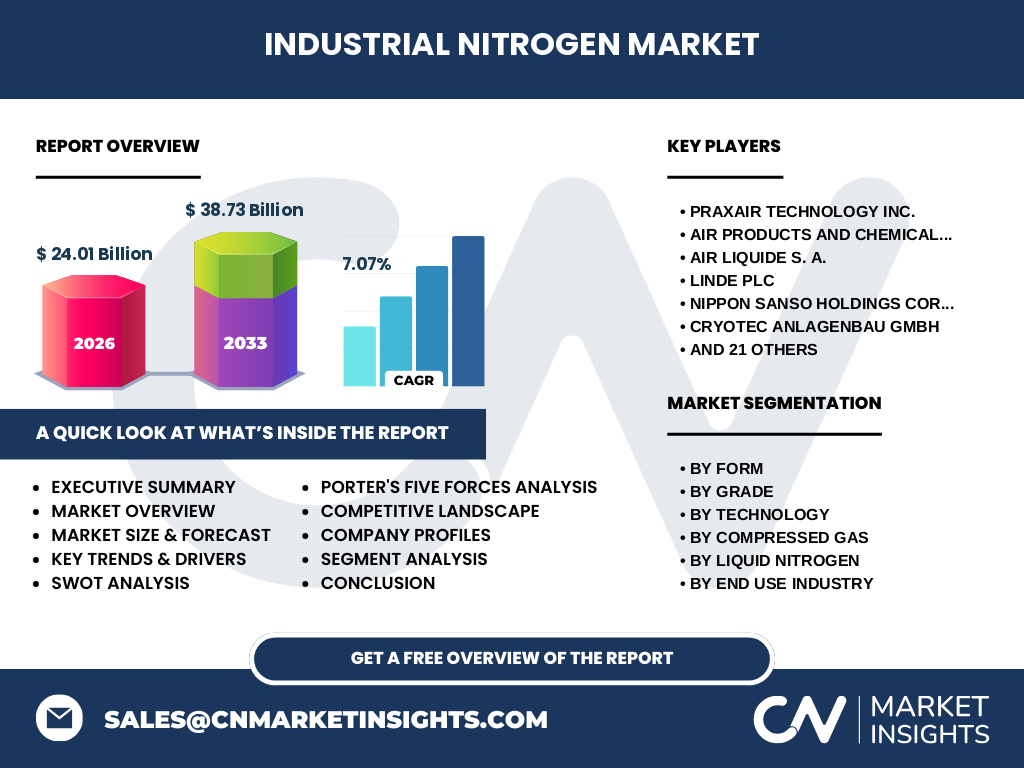
The Industrial Nitrogen Market represents a vital pillar of the global chemical supply chain, encompassing the production and distribution of gaseous and liquid nitrogen for industrial processes. With a 2026 valuation of 24.01 Billion, it serves as an inerting and cooling agent, essential for industries like electronics manufacturing and petrochemical refining. The market facilitates high-purity requirements across critical sectors, ensuring safe and stable industrial operations worldwide.
Structural Growth Drivers and Market Constraints
Growth is propelled by rapid industrialization and the rise of high-tech manufacturing, particularly within the electronics sector. Conversely, supply chain bottlenecks and the high energy costs associated with Cryogenic Fractional Distillation pose significant challenges. Our analysis indicates that companies managing these logistical hurdles via efficient pipeline infrastructure, such as Linde plc, maintain a competitive edge despite localized energy cost volatility.
Emerging Trends and Strategic Growth Patterns
The market is shifting toward decentralized nitrogen generation, utilizing advanced Pressure Swing Adsorption (PSA) and membrane separation technologies. This movement reduces reliance on bulk liquid nitrogen deliveries, favoring on-site generation. Innovations from players like MVS Engineering Pvt. Ltd. demonstrate a clear trend toward operational autonomy, allowing end-users to optimize gas purity and flow rates directly at their facility.
COVID-19 Impact and Recovery Trajectory
The pandemic caused initial supply chain fractures, particularly for bulk liquid logistics. However, the subsequent resilient recovery was driven by surging demand in the pharmaceutical and healthcare sectors for cryopreservation and inert atmospheres. By 2026, the industry stabilized at a 24.01 Billion valuation, proving that essential gas demand remains largely decoupled from broader economic fluctuations in cyclical industries.
Competitive Landscape and Strategic Dynamics
The market features high concentration levels dominated by global giants including Air Liquide S.A., Air Products and Chemicals Inc., and Linde plc. These participants leverage economies of scale in air separation units (ASUs). Smaller, regional specialists like Gulf Cryo compete by securing high-value, localized pipeline contracts, creating a bifurcated landscape where massive global footprint meets agile regional distribution.
Executive Summary: Key Findings of the Industrial Nitrogen Market
The Industrial Nitrogen Market is poised for sustained expansion, projected to reach 38.73 Billion by 2033 with a steady CAGR of 7.07%. Key findings highlight the dominance of cryogenics in high-purity applications, contrasted by the rising adoption of on-site membrane technologies. Strategic success depends on optimizing distribution efficiencies and navigating regional energy regulations to capture long-term value in the petrochemical and metal manufacturing sectors.
Market Forecast: 2027-2033 Projection
Our analysis projects that the market will scale from its current base to 38.73 Billion by 2033. This growth is underpinned by a 7.07% CAGR, driven largely by emerging economies expanding their metal fabrication and chemical manufacturing capacities. Companies that effectively scale tonnage delivery models will likely capture the majority of the projected growth as industrial throughput intensifies globally.
Segmentation Analysis: Categorizing Market Roles
The market segments into Compressed Gas and Liquid Nitrogen by form, with sub-categories for purity grades. The technology segment includes Cryogenic Fractional Distillation, PSA, and Membrane Separation. These segments dictate the distribution mode—ranging from bulk delivery to pipeline tonnage. Each segment serves distinct operational needs, with electronics favoring high-purity, while heavy industries prioritize standard-grade pipeline supply for operational scale.
Regional Market Performance and Geographic Distribution
Market performance is heavily influenced by regional petrochemical hubs and manufacturing output. While Asia-Pacific leads in consumption, North America and Europe emphasize high-purity nitrogen for specialized pharmaceutical and semiconductor applications. Regional constraints, such as regulatory emissions standards and local energy pricing, dictate the adoption speed of on-site versus bulk gas solutions across these diverse geographic markets.
In-depth Regional Review: Key Geographic Focus
Asia-Pacific remains the fastest-growing region, fueled by rapid infrastructure investment and electronics manufacturing. Middle Eastern markets show strong performance in the oil and gas sector, often utilizing bulk nitrogen for enhanced recovery techniques. Meanwhile, mature European and North American markets focus on efficiency and sustainability, pushing suppliers like Cryomech Inc. to innovate in energy-efficient cryogenic systems to meet stringent environmental mandates.
Company Profiles and Strategic Positioning
Global leaders like Air Products and Chemicals Inc. focus on large-scale tonnage projects and hydrogen integration, while specialists such as Cryogenic Industries Inc. dominate niche cooling technologies. Yingde Gases Group Company maintains strong regional dominance in Asia through aggressive capacity expansion. These companies utilize distinct capital allocation strategies, balancing massive ASU investments with targeted expansion in emerging market applications.
Porter's Five Forces: Competitive Assessment
The Industrial Nitrogen Market features high barriers to entry due to the intensive capital required for air separation plants. Supplier power is moderate, balanced by the ubiquity of atmospheric air, while buyer power is high for large-scale industrial consumers who negotiate long-term supply contracts. Competitive rivalry is intense, focused on distribution network efficiency and localized site dominance.
SWOT Analysis of the Industrial Nitrogen Sector
Strengths: Ubiquitous raw material and essential role in diverse industries. Weaknesses: High energy dependency and logistical complexity. Opportunities: Decentralized on-site nitrogen generation and green hydrogen transition. Threats: Volatile energy pricing and tightening environmental regulations from bodies like the EPA or EU-ETS. Effectively navigating these shifts is critical for incumbents to maintain their competitive, multi-billion dollar positions.
Value Chain Analysis: From Raw Material to End-User
The value chain originates with atmospheric air extraction. Value is added through high-energy-intensive processing—cryogenic or membrane—before transitioning to complex distribution via pipelines, bulk trucks, or cylinders. The final value is realized by end-users in sectors like pharmaceuticals and metals, where specific purity levels are mission-critical. Intermediaries like Sutton-Garten Co. bridge the gap between production and localized retail or industrial consumption.
Investment Insights and Strategic Recommendations
Investors should prioritize companies investing in on-site generation technologies and green energy-integrated gas plants. Given the projected market size of 38.73 Billion by 2033, the highest-potential areas reside in the transition toward small-to-mid-scale PSA modules for localized manufacturing. Strategic partnerships with key electronics and pharmaceutical firms offer the most stable long-term ROI in this capital-intensive sector.
Conclusion and Key Takeaways
The Industrial Nitrogen Market demonstrates robust health, driven by fundamental industrial needs. With a forecast value of 38.73 Billion by 2033 and a CAGR of 7.07%, the sector rewards innovation in distribution efficiency and purity precision. Stakeholders must pivot toward decarbonized production methods to mitigate energy risks while securing their footprint in high-growth, technology-driven end-use markets.
Research Methodology and Baseline Estimation
Our methodology employs a triangulated approach, synthesizing trade registry data, annual filings from industry leaders, and primary stakeholder interviews with site managers. We calibrate baseline estimates against regional macroeconomic indicators, ensuring the 24.01 Billion market sizing reflects real-world transactional volumes across various distribution modes, including pipeline tonnage and packed cylinder supply.
Scope of the Report and Coverage Parameters
This report provides comprehensive coverage of the global Industrial Nitrogen Market, spanning the 2026-2033 period. It encompasses all major grades—high and low purity—and technology categories, including Cryogenic, PSA, and Membrane. Limitations include a focus on primary industrial production; residential or small-scale laboratory niche applications are excluded to ensure the analysis remains laser-focused on significant industrial value drivers.
Recent Developments: Strategic Moves in the Market
Recent activity highlights significant M&A and capacity expansion, with major players targeting localized industrial parks to reduce transport costs. Announcements from companies like Nippon Sanso Holdings Corporation regarding new ASU infrastructure illustrate a move toward self-sufficiency in emerging regions. These strategic launches and partnerships solidify the market's trajectory toward more integrated and efficient gas delivery models, supporting the projected growth through 2033.